DSCR Loans for
Real Estate Investors

Qualify on the property's rent — not your personal income or tax returns. See which DSCR path fits your deal.

No-cost upfront rental estimate on select programs • Soft credit pull upfront • Preapprovals in as little as 48 hours • Closings in as little as 2–3 weeks

Excellent

Trustpilot

What is a DSCR Loan?

A DSCR (debt service coverage ratio) loan helps real estate investors buy, refinance, or cash out of rental property by qualifying primarily on the property's eligible rent rather than personal income or tax returns. HomeLife reviews the rent, the expected payment, credit, equity, and property details to find the option that fits the deal.
 

dscr-loans-page

How Is DSCR Calculated? 

The numbers matter — and they should be easy to understand.
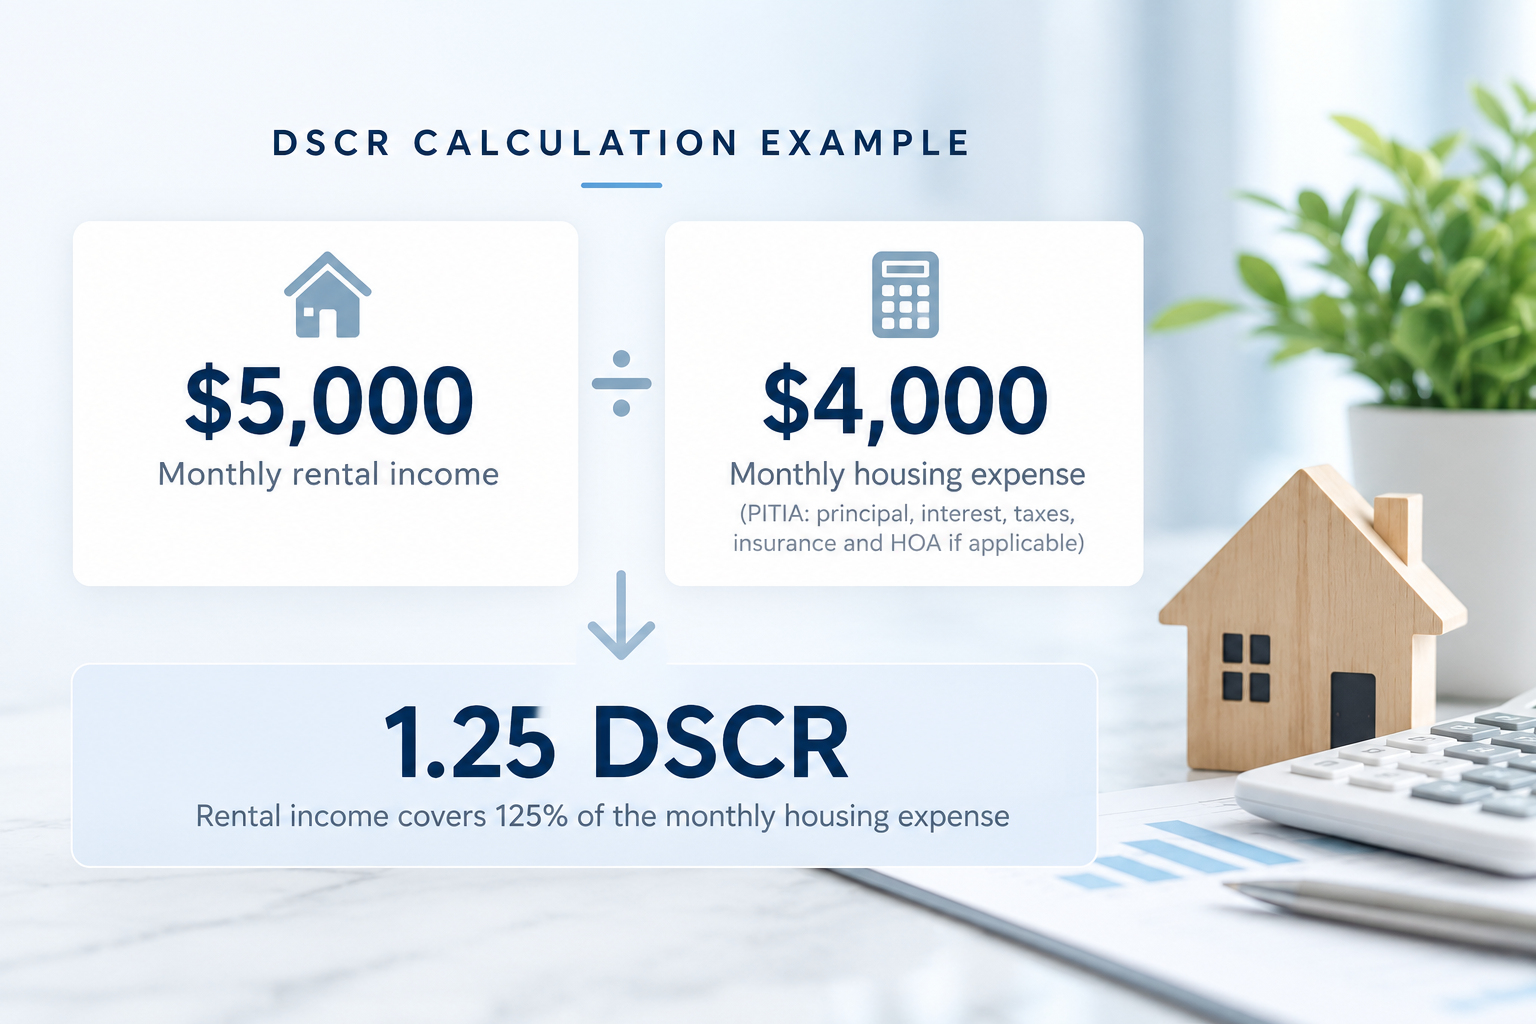
 

DSCR Calculation Infographic with House Model

DSCR = Rental Income ÷ Monthly Housing Expense

Example:

$5,000/month rent ÷ $4,000/month housing expense = 1.25 DSCR

That is a strong scenario — the property covers the debt with room to spare.

What counts in monthly housing expense (PITIA)?

Principal, interest, property taxes, insurance, and HOA dues if applicable.


Run Your Numbers - Use Our DSCR Calculator Here
 

DSCR Qualifying Lanes

1.0 or Higher:

Rent covers the qualifying housing expense. Above 1.0, it exceeds that expense.

0.75–0.99:

Flexible DSCR options may be available, with different pricing and leverage.

No-Ratio DSCR:

An option when a standard ratio is not required or does not fit the deal. Other underwriting still applies.

Can a Vacant Property Qualify for a DSCR Loan?

Yes, on some programs. A lender may use appraiser-supported market rent even when a property is vacant. HomeLife checks that path before comparing No-Ratio DSCR options.

Before You Rate Shop, Understand What Drives Pricing

DSCR loan rates aren't determined by the ratio alone. Learn how credit, leverage, property type, reserves, and loan structure can impact your rate before you move forward with the deal.

How Do You Qualify for a DSCR Loan?

Qualify using your investment property's rental income — not your personal income or tax returns. Credit, loan-to-value, and reserve requirements still apply.

Credit Score

620+

Minimum starting score; varies by loan program, property type, and LTV.

Down Payment

20%+

Eligible purchase programs may offer financing up to 80% LTV. Requirements vary by credit score, property type, and loan structure.

Additional DSCR Loan Requirements & Options

  • Documentation:

    No personal income documents or tax returns required

  • Property Types:

    Single-family, condo, townhome, 2–4 units

  • Loan Structure:

    30-year fixed; interest-only options available

  • Reserves:

    Program dependent; PITI + HOA if applicable

  • Timing:

    Preapprovals in 24–48 hours. Closings in as little as 2–3 weeks

  • Availability:

    Nationwide

loan officer calculator desk

How HomeLife Sizes Your Deal Before Appraisal

Know your qualifying rent from the start — not after you've waited on the appraisal.

  • Instant Rent Estimate

    On select DSCR programs, HomeLife can run an instant, no-cost rental income estimate (AVM) during prequalification.

  • Early DSCR Assessment

    If the estimate meets the lender's confidence requirements, it may be used as qualifying rent to calculate DSCR and assess whether the rent supports the payment.

  • Complete Deal Review

    We also review the lease or available market rent, full housing payment including applicable HOA dues, credit, equity, and loan purpose.

If the rental estimate doesn't meet the lender's confidence requirements, qualifying rent is determined using the appraiser's market rent analysis instead.

Why Investors Choose HomeLife for DSCR Loans

Multiple DSCR lenders

We shop multiple DSCR programs and know which one fits your ratio, property type, and strategy — which matters most when the deal is tight.

Non-QM specialists since 1990 —
over $4 billion funded

Darrin Seppinni is a published author, quoted by CBS News, with five HousingWire bylines. DSCR financing available Nationwide.

Buy, Refinance, or Cash Out


Asset 1-4

Buy a rental property that cash flows

Use market-rent cash-flow qualification to size a purchase before you move forward.

Asset 4-4

Rework a property you already own

Compare refinance options using market or actual rents, program dependent.

Asset 5-2

Use cash out
strategically

Access capital for rehab, reserves, or the next investment property.

Property Types and Title


Eligible property types:

  • Single-family homes
  • Condos
  • Townhomes
  • 2–4-unit properties

Title may be held in:

  • An LLC
  • A corporation
  • An individual name

Short-Term Rentals and Airbnb

For short-term rental scenarios, some lenders anchor to the appraiser's market-rent analysis. In other cases, program dependent, a lender may use an AirDNA report and annualize 100% of total annual revenue over 12 months.

The important question is simple: What income method is allowed for this deal? Clarifying that early saves time and reduces surprises.
 

AdobeStock_476476862

DSCR Loan Rates at a Glance

Your rate depends on more than the ratio — credit, loan-to-value, loan purpose, property type, and loan structure all factor in. The best rates come when rent fully supports the payment.


Darrin Seppinni
Have Questions? Ask Darrin Seppinni
Non-QM Mortgage Expert • Author • President of HomeLife Mortgage

Schedule a Consultation

DSCR Loan FAQ

If the Numbers Are Close, Let's Size the Deal Early

HomeLife can help you compare rates, requirements, and qualifying options before you spend time and money moving deeper into the file. 

Recognized as a Top Lender for
Real Estate Investors

Darrin and team is superb! I had a stress free less than 30 day closing on my new investment property purchase. They did a “No Doc” loan for me where they only had a credit report requirement. The team is very responsive and kept me updated…

Sharmila S.

“This was a complex transaction with multiple moving parts and tight timelines, yet they brought clarity to every step of the process. What could have been stressful and confusing felt seamless because of their experience and communication. They closed quickly, stayed on top of every detail, and were always available when needed.”


Diego Rojas

“After several discussions of the property and its income producing capability, Darrin suggested a No Doc DSCR loan. We are extremely pleased and satisfied with the rate and term of the facility he was able to secure for us.”

Bob Schmidt